
Heidi now needs revenue and fast. It’s going to have to be very agile and clever to keep feeding the desires of its investors and the performance criteria of its new creditor.
Last night Heidi announced that it has closed its C series investment round at $140 million and simultaneously done a private credit deal with US-based General Catalysts Customer Value Fund which, if it can hit performance benchmarks, will provide the group with access to another $340 million in working capital.
The Series C funding round, led by Blackbird with participation from existing investors including Phoenix Court, Point72 Private Investments, and Headline, values the company at $1.26 billion, up from its last valuation at its series B round of $660 million, and from a valuation point of view faster than Australian darling unicorn Canva (we do a better comparison below).
So, full speed ahead?
That’s a very big valuation number, and that’s a lot of money locked, loaded and presumably now being pointed at a large-scale go-to-market investment program to support a new phase of rapid growth and scaling.
According to Heidi’s press release, with this new funding round and debt facility in place Heidi can go about “deepening adoption across global health systems, bringing agentic capabilities to support the work around patient visits, and continuing to build the regulatory and clinical safety foundations those capabilities require”.
“That’s the shift we’re now making,” said Dr Thomas Kelly, co-founder and CEO of Heidi, in the press release, “from documenting care to helping clinicians act on it.
“This round is about getting an AI Care Partner to every doctor in the world, and putting clinicians back at the centre of care with their patients.”
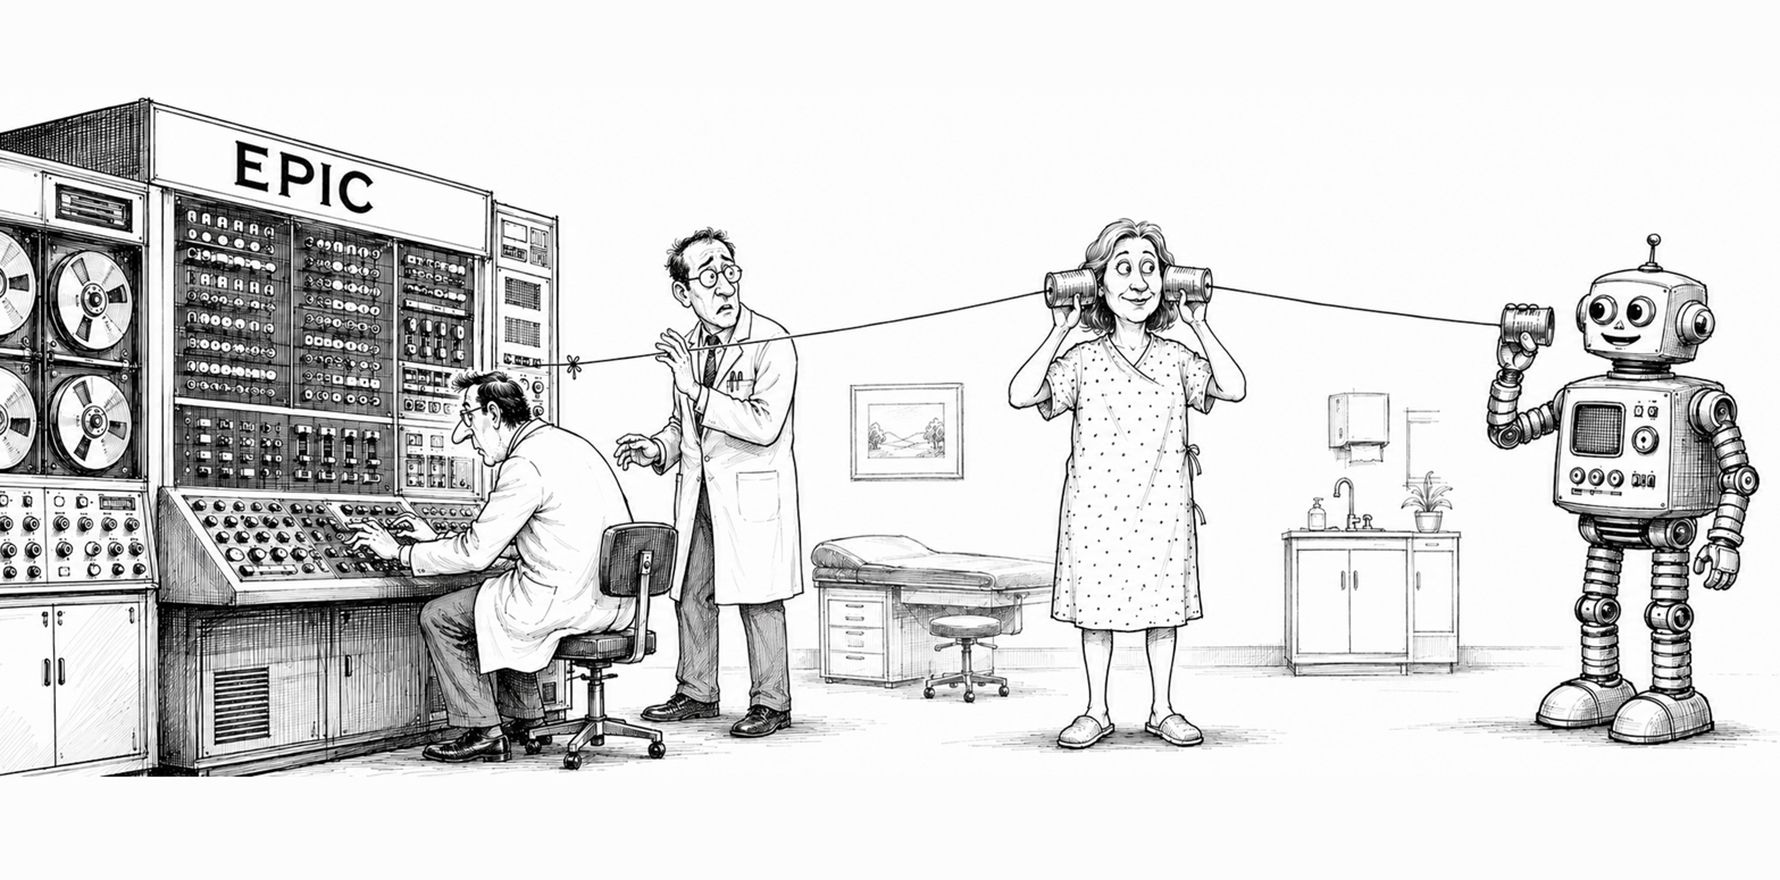
But even with $480 million in available capital, Heidi is amidst a brutal battle for AI clinical workflow supremacy, not just against massively capitalised and energised incumbent gorillas with big customer moats, like Epic and Oracle, but against literally scores of other AI clinical workflow pretenders, many with better existing market positions in the markets that count, the US, UK and EU, and more money to blow.
In the US, Heidi’s position is still early-stage. Its main disclosed US health system customer is Beth Israel Lahey Health in Massachusetts, a legitimate enterprise deployment but one where the underlying EMR is Oracle Cerner.
Oracle is actively developing its own ambient AI documentation capability. The question of how long enterprise health systems maintain a separate ambient AI contract alongside a native EMR product from their own vendor is one that has a long way to play out.
Heidi’s KLAS report – cited in its promotional materials – was an “Emerging Company Spotlight”, a customer satisfaction survey of Heidi’s own nominated customers rather than a market ranking.
Heidi was too small to be included in KLAS’s main US ambient AI market comparison at the time.
In the US, Nuance DAX, Ambience, Nabla and Abridge all have deeper enterprise penetration and, in most cases, native EMR write-back integrations that Heidi is still developing and has yet to deploy anywhere.
In the UK, Heidi has momentum with the NHS Midlands win, but faces strong competition from TORTUS AI, Accurx, Nuance Dragon Copilot and even local group Lyrebird, which has won a contract to integrate with four of London’s big hospitals.
Heidi Evidence, its clinical knowledge product, cannot be used in the UK or EU for regulatory reasons. In Australia, it is locked out of the dominant GP market by Best Practice’s investment in Lyrebird and MedLuma, as we reported this week. And it’s up against Doximity, OpenEvidence, UpToDate, ClinicalKey, ChatGPT Health and Claude Health in terms of competing in clinical knowledge.
Having said all this, even if Heidi can’t get a foothold where the big players are established, there appears to be a wide open market for AI clinical workflow in mid-market to small hospitals that don’t have established EMRs and in just about every GP and specialist market you can name in some form or another, other than Australia which looks locked up. And Heidi is going for an even wider spread into allied health, aged care and markets like our NDIS.
With all that money and the right dodging and weaving, that might make it, especially given they are very agile and innovative, which is something nearly all the incumbents are not.
In a recent LinkedIn post prolific medical AI commentator Joshua Lui had this to say on the current state of play:
“Epic is under extreme pressure to catch up to startups on R&D and major trade-offs are being made. In the past the ‘announce we’re doing X, release the MVP and buy time to iterate’ worked well for Epic – but in the AI era where startups have hundreds of millions in VC money and are siphoning up the best AI talent, this strategy is more precarious.”
He said this about the AI start-ups though:
“…the VC-backed startups … are under extreme pressure to grow revenue even though Epic has frozen the market for new customers (everyone without an ambient partner will try Epic’s AI first), Oracle pushes their own AI clinical agent first, and MEDITECH is doing similar. VCs will demand extreme revenue growth to justify the massive valuations, and I don’t understand how startups can meet those expectations without upselling existing customers on … new features.”
So, there’s a way through, but it looks like Heidi is going to have to be pretty tactical in threading a few moving needles. Certainly, its PR bluster about ruling the world of clinical AI doesn’t seem like a feasible aspiration on what looks like a complex and dirty battlefield with lots of different armies wanting to stake out land.
What could go wrong?
The $140 million in new investment, in relative terms to the above listed players isn’t actually a lot, which means the private credit $340 million debt facility is important.
But private credit isn’t cheap and it’s almost always a staged line of credit pending the lender hitting pre-determined benchmarks.
The General Catalyst arrangement is debt not equity, structured as a revenue share arrangement rather than a conventional loan. General Catalyst funds Heidi’s sales and marketing costs to acquire new customers, then recovers its capital plus a return of something like 16-18% from the revenue those customers generate, up to a fixed cap.
The $340 million is almost certainly tranched, with each draw requiring demonstrated milestones – ARR thresholds, enterprise deployment targets – before the next tranche is released. It is a ceiling on what may be available, not a guarantee of what will be received.
It is also worth noting that global private credit markets are under a lot of duress at the moment, with significant capital concentrated in property-related debt at a time of rising rates and falling valuations.
Related
General Catalyst’s CVF is a different instrument, but the broader market context adds a layer of risk to any facility of this kind.
A big risk here for everyone is that big AI – ChatGPT, Claude, the hyperscalers, the chip makers – is one big fat new financial bubble that pops in the not-too-distant future.
If that happens, likely that debt facility will go south and Heidi will be stuck eking out its $140 million of investment capital.
Whether Heidi sees the debt capital in full depends almost entirely on whether it converts procurement announcements into paying, active users at scale and hits the milestones that trigger each tranche.
No new major US institutional fund has led with an equity cheque (ie, there are no new investors in this announcement).
Notably, the press release does not disclose how much each investor contributed.
Existing investors following on at a small amount is structurally different from a US fund making a significant new commitment at a US$900 million valuation. We do not know whether Point72’s participation represents a meaningful pro-rata follow-on or a more modest show of continuing support.
An important component of the announcement everyone needs to understand better is the claim that Heidi has an “enterprise activation rate” of around 62% across major public and private health systems since its Series B.
That number deserves scrutiny before it becomes a received fact.
The NHS England Midlands procurement – described by Heidi’s PR department as the largest clinical AI procurement in NHS history, covering 70,000 clinicians across 15 trusts – was announced in July 2026, and is starting from scratch and only actually covers five trusts at the outset.
The Australian hospital deployments named in the release are recent. The New Zealand emergency department rollout is new.
A 62% activation rate across enterprise health systems that have only recently been announced as procurement partners feels like a pretty bold claim.
The Medical Republic is seeking clarification on how that figure is calculated, specifically, whether it reflects the proportion of licensed clinicians actively using the product or the proportion of contracted institutions that have initiated any deployment activity at all and what of that is free and what is paid for.
Heidi’s current commercial position is that it has strong individual clinician adoption – its viral, word-of-mouth model has been genuinely impressive – and a growing set of enterprise procurement commitments.
What it has not yet demonstrated is that those commitments convert to large, sticky, deeply integrated revenue contracts that justify a US$900 million valuation and support the deployment of $340 million in staged private credit.
The ARR trajectory from $1.4 million to $70 million in two years is real and remarkable.
The question the funding structure implicitly poses is: can it do the same again at an order of magnitude greater scale, in markets where it is not the incumbent, against competitors with native EMR integration, in a regulatory environment where its clinical knowledge product faces restrictions, with a private credit facility that only pays out if the customers materialise?
One financial adviser consulted by this publication, who has experience in both private equity and private credit markets, declined to invest in Heidi at the current valuation, noting the company is well run and may well succeed, but that US$900 million prices in an execution at scale that has not yet been demonstrated in the markets where it matters most.
The same observation could have been made about Eucalyptus before its $1.15 billion acquisition by Hims & Hers, a reminder that valuation scepticism and eventual success are not mutually exclusive.
But Eucalyptus had something Heidi does not yet have: a large, paying direct-to-consumer revenue base that was genuinely difficult to replicate quickly.
The Canva comparison that Blackbird and Heidi’s own communications lean on doesn’t hold up too well either.
The AFR’s claim that Heidi has grown faster than Canva refers specifically to ARR velocity. Heidi went from $1.4 million to $70 million ARR in approximately two years, which Blackbird says is the fastest they have seen.
But on most other metrics, the comparison falls a bit flat. Canva hit unicorn status at its Series C in January 2018 while already profitable. It had been profitable since 2017, generating real, recurring subscription revenue from tens of millions of users with no dependence on enterprise procurement cycles or expensive private credit to fund growth.
Canva also faced a genuinely narrow competitive field at that stage: Adobe was the dominant incumbent and essentially the only serious rival.
Heidi is operating in a market with scores of well-capitalised competitors globally – Nuance DAX (backed by Microsoft), Ambience, Abridge, Nabla, Suki, and a rapidly expanding list of EMR-native products from Epic, Oracle, and Best Practice.
The dynamics of winning in this field are categorically different from what Canva faced.
The comparison is typical of Heidi’s well-oiled PR machine. It’s been great at PR. Great PR helps to raise money no doubt.
But it’s not a reliable guide to Heidi’s commercial prospects.
None of this is to say Heidi will fail. The technology is good, clinicians genuinely fall over themselves with love for it, the clinical outcomes data seems credible, it is building some enterprise footprint and it has so far consistently outpaced even optimistic forecasts.
But this $480 million announced is not $480 million received.
Heidi now has to grow faster than it ever has but it’s facing very stiff headwinds in established EMR incumbent markets and the more greenfield market of mid-market hospitals and general practice just don’t move that fast generally on adopting new technology.
Heidi now needs revenue and fast. It’s going to have to be very agile and clever to keep feeding the desires of its investors and the performance criteria of its new creditor.
